Key Announcement Overview
On October 1, 2026, market research firm Omdia published its India PC & Tablet Market Quarterly Report. Key facts:
- Release date: October 1, 2026 (London time)
- Coverage period: Second Quarter 2026 (2Q26) and full-year outlook
- Key figures: PC shipments 4.1 million units (+14% YoY), notebooks 3.0 million (+13%), desktops 954,000 (+15%), tablets 1.3 million (+11%)
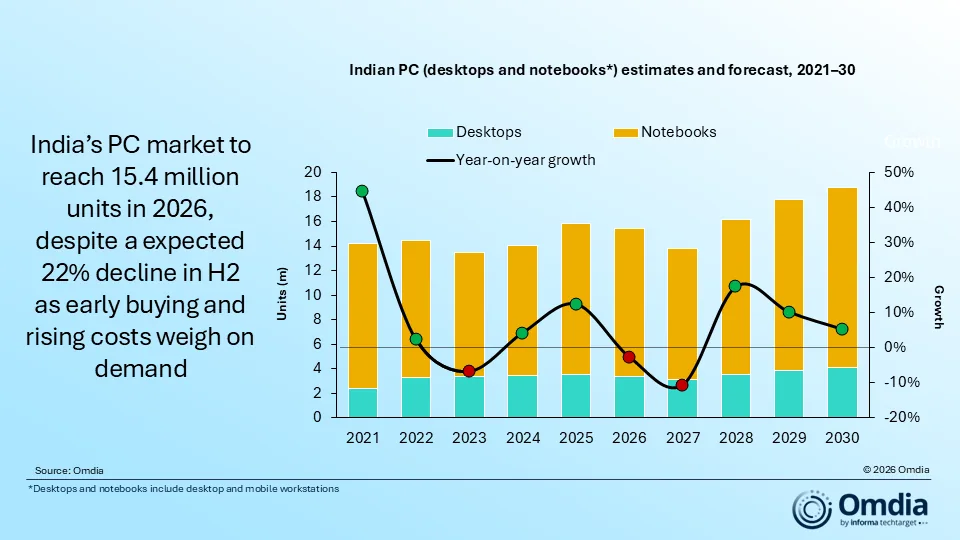
- Full-year forecast: PC market 15.4 million units (-2.6% YoY), tablet market 5.1 million units (+4.2% YoY)
Market Performance: Q2 Growth, H2 Decline Forecast
India’s PC market grew 14% year-on-year in Q2 2026, reaching 4.1 million units shipped: notebooks at 3.0 million (+13%), desktops at 954,000 (+15%), and tablets at 1.3 million (+11%). This growth reflected front-loaded purchases by channel partners seeking to secure inventory before expected price increases later in the year.
“The growth in Q2 looks strong on the surface, but much of it reflects purchases brought forward by both end customers and channel partners to secure PCs before the next round of price increases,” said Omdia Senior Analyst Ashweej Aithal.
Notable reversal: Despite the full-year PC market forecast to decline 2.6%, education sector notebook shipments surged 191% in Q2, serving as a major growth driver. Commercial PCs jumped 19%, significantly outpacing consumer PCs (+8%), showing resilient enterprise demand.
Similarly in tablets, Apple’s shipments grew 35% and Lenovo’s grew 89.9%, both gaining market share. Omdia noted the market is shifting toward higher-value devices: consumer shipments grew 12% (driven by premium/newer models), commercial 11% (SMB-led), and enterprise remained stable.
Sales Structure and Price Pressures
AI capability has become standard in new products: AI-capable notebook share rose from 28% to 44%, signaling rapid adoption of newer configurations.
Price pressure is abnormally concentrated on entry-level PCs. Omdia forecasts component cost increases will most heavily impact budget devices, where Indian consumers demonstrate high price sensitivity. Vendors are adjusting configurations to maintain key price points and limit cost pass-through.
A tiered market segmentation is emerging:
- Premium and gaming PCs: Better able to absorb cost increases, demonstrating stable demand
- Enterprise buyers: Continuing necessary fleet refreshes with higher-spec notebooks
- SMBs: Engaging in front-loading behavior ahead of anticipated H2 price hikes
- Budget-conscious consumers: Possibly delaying upgrades or opting for lower-spec models
Apple’s PC (MacBook) shipments are expected to see the smallest decline, supported by its premium positioning, tight hardware-software integration, and loyal installed base.
Tablet challenges center on the education segment: government tender delays and component cost inflation led to a 12% shipment drop, explaining the sustainability concerns around Q2’s overall robust growth.
Full-Year Outlook and Long-Term Trends
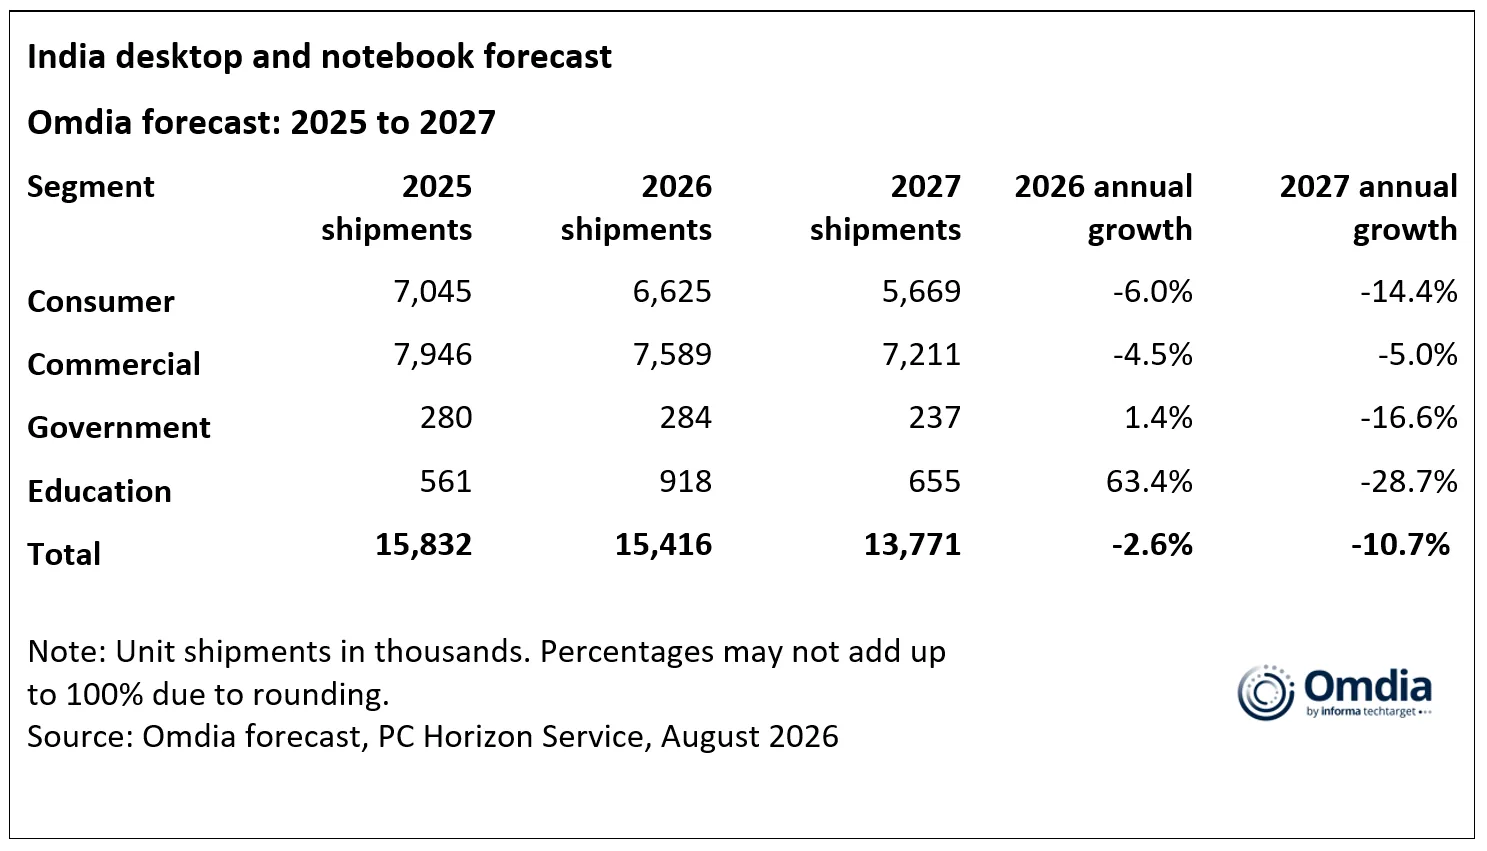
| Metric | 2026 Full-Year Forecast | YoY Change | Q2 Reference (2Q26) |
|---|---|---|---|
| PC total shipments | 15.4 million units | -2.6% | 4.1 million (+14%) |
| Consumer shipments | - | -6% | 8% growth |
| Commercial shipments | - | -5% | 19% growth |
| Education shipments | 918,000 units | +63% | 191% growth |
| Tablet total shipments | 5.1 million units | +4.2% | 1.3 million (+11%) |
The full-year outlook retaining structural brightness: education procurement estimated at 918,000 units (+63% YoY); though H2 growth will moderate as government projects conclude, Q2’s strong base supports the annual target.
Long term, India’s tablet outlook is more positive. Omdia believes tablets are approaching entry-level PC user experience via larger displays, better specs, and productivity use cases. Manufacturing evolution is also notable: Samsung and Lenovo already leverage local production for overseas exports, with other brands expanding local manufacturing footprint—an advantage for supply-cost management as domestic demand becomes more price-sensitive.
Reader Recommendations
- Buy now if: enterprise IT departments or SMBs seeking favorable pricing before H2 expected hikes, or Apple ecosystem users valuing/model stability of MacBooks with AI features;
- Wait if: budget-conscious individual buyers facing potential entry-level PC price pressure, awaiting H2 promotions or new model refresh cycles;
- Strategy: prioritize configuration value over list price, given vendor tuning to maintain anchor points despite component inflation.
Final Thoughts
India’s PC and tablet markets are undergoing structural divergence: high-end and commercial products show resilience, while entry-level segments face dual pressure from costs and demand elasticity. Enhanced local manufacturing offers supply-chain flexibility, but sustained growth hinges on the balance between component cost pass-through and government tender cycles.
Source: Omdia official report, October 1, 2026. Link: https://omdia.tech.informa.com/pr/2026/sep/indias-pc-market-growth-set-to-reverse-with-22percent-decline-forecast-in-2h26